Indian Automobile Sector: Overview, Growth & Outlook
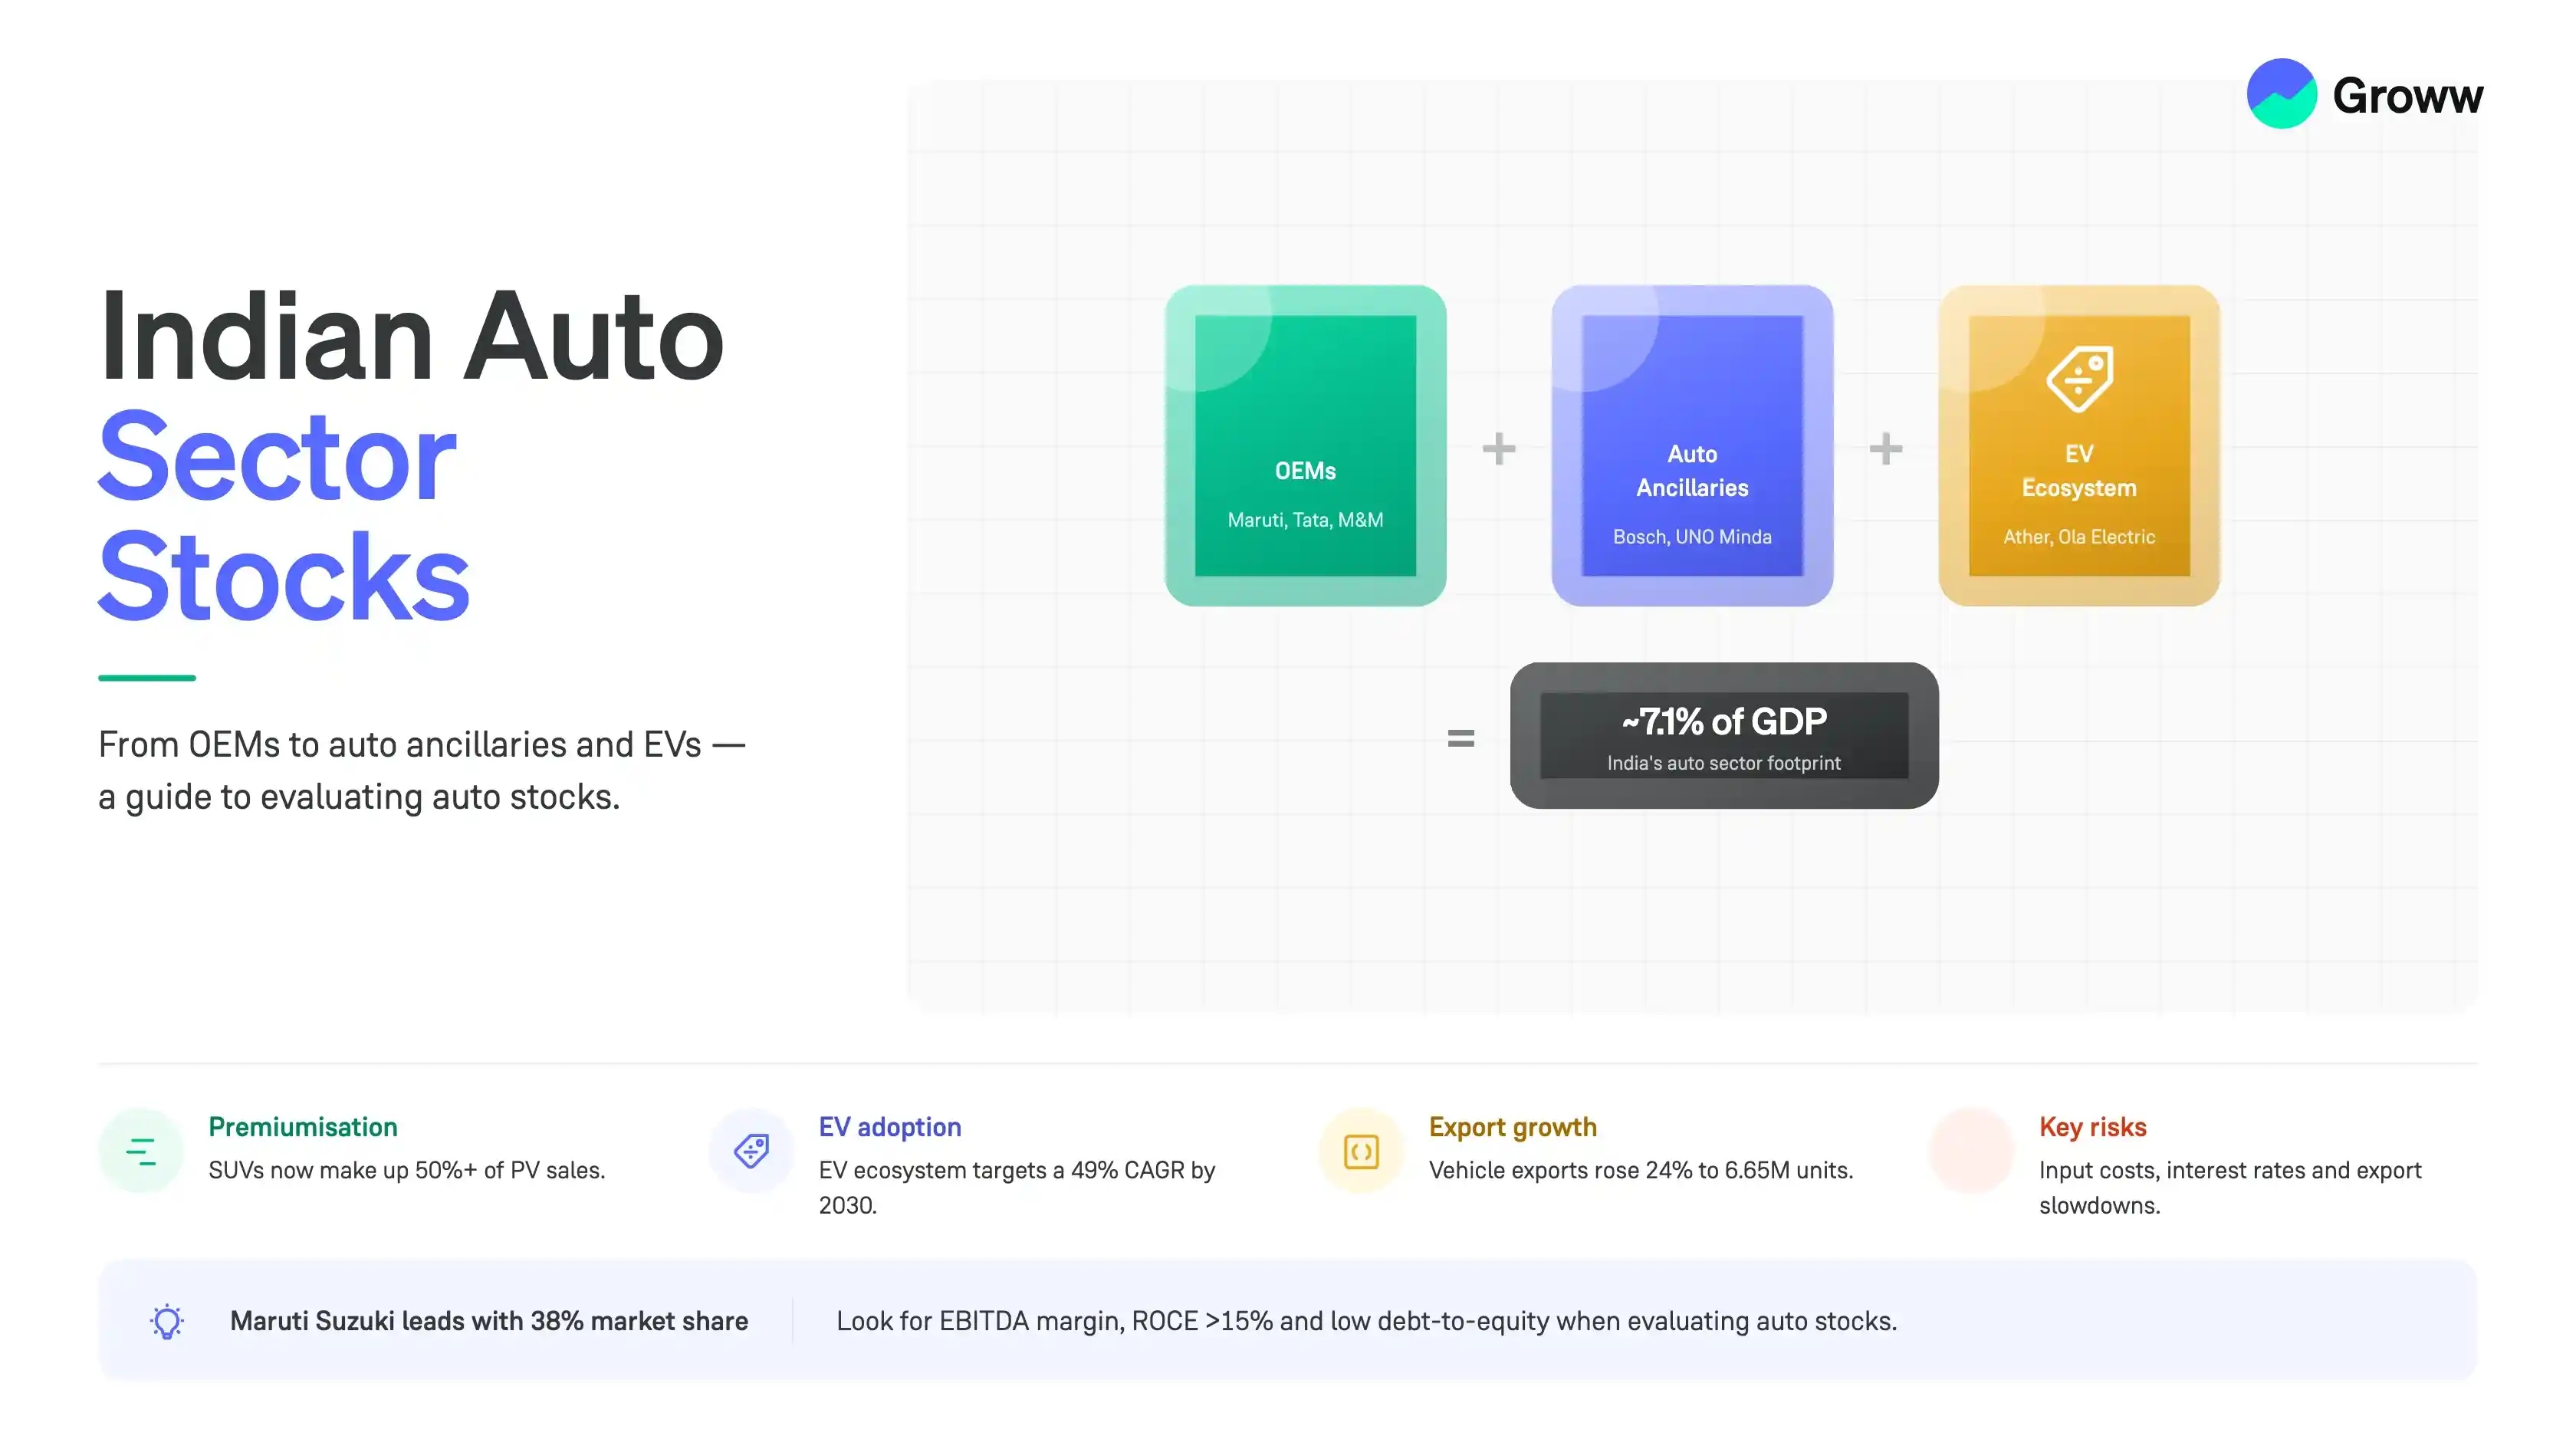


As of mid-2026, the Indian automobile sector is witnessing strong growth driven by premiumisation, the dominance of SUVs, and the accelerated adoption of electric vehicles (EVs).
FY25 saw more than 5.3 million vehicle exports, while the industry is moving towards electric, smart and connected vehicles, with key players such as Mahindra, Tata and Maruti Suzuki.
Mid-size SUVs remain the biggest-selling category, with the sector supported by rising domestic consumption, robust GDP growth forecasts (>7%), and strong rural demand. Customer demand is swiftly shifting towards safe, premium vehicles, including high-tech and luxury features.
The NSE EV and New Age Automotive Index were also launched in May 2024, tracking the performance of companies in the EV ecosystem and the new-age automotive segment. The index includes companies engaged in EVs, battery technologies, and charging infrastructure. This works as a benchmark for passive funds and asset managers.
As of early May 2026, the Nifty EV & New Age Automotive Index is trading around the 3,000-3,075 level, which reflects a positive 1-year return of more than 9-10% along with robust 1-month gains. The EV sector is flourishing, with forecasts indicating that the Indian market will see a significant increase in valuation by 2032.
Here are some key facts and figures about the Indian auto sector:
- In FY2026, the Indian automobile industry posted record sales across multiple categories, driven by GST reforms, the growing popularity of SUVs, and rural demand.
- Total PV sales figures touched approximately 4.64 million to 4.7 million units (13% year-on-year growth), while two-wheelers witnessed 10.7% growth to 21.71 million.
- Two-wheelers increased by 10.7% while commercial vehicles grew by 12.6%. Electric passenger vehicle sales grew by 75.14% in April 2026, although they accounted for just 4.6% of the total car market in the first quarter.
- Maruti Suzuki leads with 38% market share, followed by Tata Motors (15%) and Mahindra (13.9%). SUVs also accounted for 50%+ of passenger vehicle (PV) sales.
- Vehicle exports also rose by 24% to 6.65 million units.
Emerging themes in the auto sector
Bharat Stage VI Emission Norms
The Bharat Stage Norms are standards instituted by the government of India to regulate the emission of air pollutants from motor vehicles. The norms were introduced in the year 2000 and are based on similar norms in Europe called Euro 4 and Euro 6. As on April, 2017, all vehicles were mandated to adhere to BS IV Norms.
The new government policy mandates that by April, 2020 all vehicles must be complaint with BS VI Norms. The introduction of BS VI Norms calls for upgradation in the technology which helps reduction of emission of pollutants. BS VI also makes on-board diagnostics (OBD) mandatory for all vehicles. OBD device informs the vehicle owner or the repair technician how efficient the systems in the vehicle are.
Compliance with BS-VI norms will require higher investment in technology to upgrade vehicles in stock and those which are newly produced. This has dual implications. One is that there will be fewer new launches till the deadline. Secondly the prices of the newly introduced vehicles from April, 2020 will be higher since the vehicles will cost automakers more and they will pass on the additional cost to the buyers. The Bharat Stage VI-compliant fuel too will also be more expensive. This is likely to impact the overall demand in this sector at least during the period which is in proximity to the deadline.
In order to provide ease in the process towards compliance, many auto makers moved then Honorable Supreme Court which reject their plea and upheld the validity of the deadline.
New third party insurance norms
In line with the Supreme Court order in this matter, the IRDAI (Insurance Regulatory and Development Authority of India) directed all general insurance companies to offer only long term third party insurances for motor vehicles. As per this direction, general insurance companies are directed to issue only three-year insurance for 4 wheelers and five-year insurance to two wheelers. The direction also mandates the premium for the entire term be collected in the beginning at the time of sale of vehicle itself. The amount so paid in excess of first year premium would be considered as “Premium Deposit” or “Advance Premium” and be recognized as income upon maturity of the relevant period for which the premium is paid.
This has led to increase in premium itself in addition to increasing the burden of new purchase. Hence, this has been considered as one of the contributing factors to the weakening demand. However, as the policy changes are gradually absorbed the negative impact due this rise in insurance premium is expected to subside.
FY2024-25 Sales Trend From the Society of Indian Automobile Manufacturers
Here are the key sales trends from the Society of Indian Automobile Manufacturers (SIAM) for FY2024-25 (April 1, 2024-March 31, 2025) -
- Domestic sales (overall): 7.3% growth.
- Passenger Vehicles: Highest-ever sales of 4.3 million units (2% year-on-year growth), while UVs (utility vehicles) accounted for 65% of total sales.
- Two-wheeler: Robust recovery with 9.1% growth and 19.6 million units.
- Three-Wheelers: Highest-ever sales figures of 7.4 lakh units with 6.7% growth driven by e-vehicles and last-mile connectivity.
- Commercial Vehicles: Marginal de-growth (-) of 1.2% in domestic sales, touching 9.57 lakh units in all.
- Exports: Grew by 19.2% across all segments.
- Electronic Vehicles: Total registrations reached 1.97 million, up 16.9%.
- Inventory Levels: 50-55 days (high) in Q4 for PVs, putting pressure on manufacturers' working capital.
How to Evaluate Auto Stocks
Here is a structured approach that could help you with smartly evaluating auto stocks:
Key Financial Metrics
- EBITDA margin: An indicator of profitability from core operations after deducting costs of raw materials.
- Debt-to-equity ratio: Low debt is vital, particularly for component makers.
- Return on capital employed (ROCE): It should be as high as possible (>15%) for auto companies to ensure good returns on the capital they invest.
- Inventory Turnover Ratio: Indicates how efficiently the firm manages stocks and sales.
Operational & Market Metrics
- Monthly sales volumes: Track monthly, yearly and monthly sales volume growth.
- Market share: Analyse whether the company is scaling market share in its category.
- Production utilisation rate: Tracks the effective utilisation of manufacturing plants.
Sector-Specific Drivers
- Monsoon & rural demand: Good monsoon rainfall will naturally drive higher sales of two-wheelers and tractors.
- Government incentives & policies: Track scrappage policies, FAME subsidies for EVs, GST, etc.
- Raw material costs: Fluctuations in rubber, steel, aluminium, and other materials may impact margins.
- EV transition blueprint: Evaluate companies based on their R&D investments, EV product pipelines and charging infrastructure blueprints.
Stock Categorisation (Examples)
- PVs (Passenger Vehicles): Tata Motors, Mahindra & Mahindra, Maruti Suzuki
- Two-Wheeler: Bajaj Auto, Hero MotoCorp, TVS Motor
- Commercial Vehicle (CV): Tata Motors, Ashok Leyland
- Auto Ancillaries/Components: UNO Minda, Sona BLW, Bosch, etc.
You can also use the Nifty Auto Index to track overall industry performance and market sentiments.
OEMs vs Auto Ancillaries vs EV Ecosystem
The Indian automobile sector contributed about 7.1% to GDP and is a vital, high-growth landscape divided into auto ancillaries (component suppliers), OEMs (vehicle assemblers), and a fast-growing EV ecosystem.
Here is a breakdown of the major segments:
- OEMs (Original Equipment Manufacturers)
These are the companies that assemble the final vehicles, with major players including Mahindra, Tata Motors, TVS, Maruti Suzuki and Bajaj Auto. Their focus areas are branding, product development, distribution and marketing. They are also expanding their EV portfolios and adopting newer technologies.
- Auto Ancillaries
They are the component suppliers and the backbone of the sector, offering essential parts such as transmissions, wiring, and engines. They are major exporters and are steadily switching from ICE (internal combustion engine) frameworks to EV-based components.
- EV Ecosystem
This includes EV OEMs like Ather and Ola Electric, as well as battery manufacturers. It also includes software developers and providers of charging infrastructure. They are backed by Government initiatives such as PM E-Drive, FAME, and PLI schemes. The segment is also anticipated to grow at a 49% CAGR (compound annual growth rate) by 2030, with EVs expected to reach 10 million annual sales by this period.
|
Aspect |
OEMs |
Auto Ancillaries |
EV Ecosystem |
|
Role |
Final assembly and branding |
Suppliers of components |
Providers of future mobility |
|
Market |
High domestic market and exports |
High domestic market and exports |
Quickly growing with high future potential |
|
Main Drivers |
Ownership and Urbanisation |
Affordability and Quality |
Technology and Government Policies |
|
Outlook |
Structural Growth |
High-Value Additions |
Disruption and Innovation |
Why the Auto Ancillary Sector Stands Apart
Investors can view auto ancillary stocks separately as they often could offer better margins, higher growth potential, and lower risk than OEMs (original equipment manufacturers). Let’s look at some of these aspects in more detail below:
- Kit Value Expansion and Growth Possibilities
Ancillary companies are scaling up kit value (total components per vehicle) by 3-4 times by switching from simple parts to higher-value, more advanced systems.
- High Moat or Sticky Business Model
Automakers very rarely switch their suppliers once any product has been integrated. This offers ancillary firms robust, long-term visibility into revenue.
- Lower Risk and Diversification
Unlike OEMs, which may rise/fall with one brand’s sales figures, many ancillary firms supply several automakers. This lowers company-specific risks and helps diversify your portfolio.
- EV Transition Benefits
While ICE parts are threatened by EVs, many ancillary companies are already switching to supply motors, batteries and infotainment systems. This allows them to benefit from the EV shift, no matter which OEM ultimately wins the race.
- Export Growth Potential
Many Indian ancillary companies have strong export volumes, offering a hedge against downturns in the domestic auto sector.
OEMs vs Auto Ancillaries: Key Differences Explained
|
Aspect |
OEM |
Auto Ancillary Company |
|
Role |
Assembling the final vehicle, branding, distribution, and marketing |
Producing components |
|
Risk Profile |
High (Intense competition and cyclicality) |
Moderate (diversified client base) |
|
Potential for Growth |
Moderate (tied to domestic sales) |
High (tied to exports and premiumisation) |
|
Margin Profile |
Lower margins (more intense price wars) |
Higher (more stable margins) |
|
EV Impact |
High capital expenditure is needed |
Higher opportunity with new components needed |
|
Main Drivers |
Demand, brand value, new launches |
Global outsourcing, EVs and innovation |
|
Top Stocks |
Maruti Suzuki, Mahindra & Mahindra, Tata Motors |
Bosch, UNO Minda |
|
Target Sector |
Passenger and Commercial Vehicles + Two-Wheelers |
Diversified across OEMs and Aftermarket |
Rural demand outlook
The rural demand been providing the much needed support to the melancholy of the sector. The overall increase in government spending has been a major contributor to the increase in consumption demand in the rural space. There have been a number government initiative such as rising of the MSP (Minimum Support Price) for Kharif crops, increased rural infrastructure spending, etc., which have contributed to this rise in rural demand.
Other policy impact
The Society of Indian Automobile Manufacturers (SIAM) provides posits a positive outlook towards the recent interim budget with respect to the auto sector. The tax exemption up to 5 lakhs is likely to increase the disposal income of the middle class and have an impact on sales volumes of two wheelers and small four wheelers.
However, the budget also introduces customs duty on lithium ion batteries from nil to 5%. This will be disadvantageous to the e-vehicle segment which is at a very nascent stage in India.
The sector is also largely influenced by the interest rate regimes, as it affects cost of capital, EMI rates, cost of financing etc. After a series of rate hikes amidst weakening rupee and rising commodity prices and inflation, in February, the RBI cut rate by 25 bps (basis points) for the first time. With the reduced pressure on inflation, this is likely to impact the auto sector positively.
Overview of the sector performance
The NSE Auto Index data has recorded a fall from 11000 levels to as low as 8500s in the period between August, 2018 to November, 2018. It is pertinent to observe the movement of oil prices in the period. During this period the crude oil prices rose as high as $85 per barrel. The period was also marked by poor performance of the rupee and rising interest rates. Adding fuel to the fire, consumption demand in the Diwali season also fell below expectations. The relative stabilization of these factors is being gradually absorbed by the market. New product launches, reviving consumption demand and base effect posit a scope for improvement in this space.
However, it would also be pertinent to note that this revival is not reflected in the market sentiment. Over the past 6 months the price to earnings ratio (PE) of the index has fallen from 30 to 23 vis a vis Nifty 50 which has been trading at an average of 25-26. A selling spree can be observed among the institutional investors as well, wherein large number of mutual funds are dumping auto stocks from their portfolio.
From a fundamental performance point of view also, the sector as a whole has not reported good numbers. This could be a fall out of the various factors discussed above. While analyzing the sector it is crucial to look at the volume of sales inter alia other factors such as inventory turnover, debt equity ratio etc.
Key Factors Fueling Growth
The Indian automobile sector is witnessing strong growth with a CAGR of 8.63% (between FY16 and FY24). It is also expected to witness steady growth in FY26-27 through new launches and infrastructure expansion.
Here are some of the main factors driving growth:
- Premiumisation and SUV Demand
Consumer preferences are rapidly shifting towards high-end models, SUVs, and vehicles with strong features, thereby enhancing margins.
- Rural Demand and Two-Wheelers
Sustained rural demand, driven mainly by rising incomes, continues to boost the PV and two-wheeler categories.
- Expansion of Exports
India is gradually strengthening its position as a hub for global exports, with automotive component exports forecasted to touch US$30 billion by the end of 2026. This will be driven by increasing demand for manufactured goods.
- Financing and Penetration into the Market
Accessible credit, attractive financing options, and a fast-growing middle class are also scaling vehicle ownership penetration.
- EV Adoption and Ecosystem Development
More than 4.4 million registered EVs are already in use, with rising adoption of 2W/3W models. The PLI and PM E-DRIVE schemes back localisation, while GST has been reduced to 5% on EVs. Efforts are underway to boost charging infrastructure, inclusive of FAME II initiatives.
Valuation and Cycle Awareness
Here are some aspects related to cycle awareness for the Indian auto sector:
- Upcycle Drivers: Growing middle-class, robust PV/SUV demand and urbanisation.
- Downcycle Indicators: Weak monsoon (low rural demand), rising interest rates, and high costs of raw materials.
- Timing the Cycle: The best time to invest is early expansion (low capacity utilisation) and to sell near the peak (high capacity utilisation).
- Long-Term Drivers: Shift towards EVs and Government initiatives like PLI schemes for EV manufacturers and auto components.
Here are the key metrics regarding valuation:
- EBITDA Margin: Ideally 12-15% for PVs.
- ROCE: Look for companies that maintain a ROCE above 15% across cycles.
- Key Metrics: Track market share expansion, revenue growth, P/E ratios and other metrics compared to the industry averages.
Best Auto Stocks by Segment
Here is a guide to the best auto stocks by segment as per market capitalisation for your perusal:
|
Segment |
Company/Stock |
Market Capitalisation (as of May 8, 2026, in Cr) |
|
Passenger Vehicle |
₹4,31,377 Cr. |
|
|
₹4,10,364 Cr. |
||
|
₹1,31,831 Cr. |
||
|
₹1,49,536 Cr. |
||
|
Two-Wheeler |
₹2,88,290 Cr. |
|
|
₹1,71,879 Cr. |
||
|
₹1,03,442 Cr. |
||
|
Commercial Vehicle |
₹2,00,560 Cr. |
|
|
₹1,58,082 Cr. |
||
|
₹98,622 Cr. |
||
|
Auto Ancillaries |
₹1,34,041 Cr. |
|
|
₹1,08,150 Cr. |
||
|
₹65,550 Cr. |
||
|
₹65,110 Cr. |
||
|
EV Ecosystem |
₹34,341 Cr. |
|
|
₹15,358 Cr. |
||
|
₹10,462 Cr. |
Here are some key aspects of the segment-wise performance and outlook:
- EV Market Exposure
High-exposure stocks include Tata Motors, Ola Electric and TVS Motor. Ancillaries like Bosch and UNO Minda are also supplying components.
- EBITDA Margins
Anticipated to remain robust for SUVs and premium 2Ws, while Bajaj and TVS (among 2W makers) show improvements due to EV cost optimisation.
- Volume & Export Mix
TVS and Bajaj have high export exposure. PV volume is mainly driven by the premiumisation of SUVs, with Maruti Suzuki and Mahindra & Mahindra being the dominant names.
- Dealer Inventory
Trending towards optimised levels, moderate inventory was reported early in 2026.
- Debt & ROCE
TVS and Mahindra & Mahindra lead in ROCE (return on capital employed). Several big OEMs are also maintaining low debt levels compared to earlier cycles.
Major Challenges and Risks
Some of the key risks for the sector include the following:
- Inflation & Commodity Costs
Geopolitical tensions are driving up the costs of raw materials, with commodity prices already expected to cut 100 basis points off margins for FY27.
- Financing & Interest Rates
Possible interest rate adjustments and economic volatility affect consumers' purchasing power. While lower borrowing costs were helpful in FY26, high rates remain a major risk to future demand.
- Regulatory Compliance & Changes
The complex and rapid shift to EV mobility and changing emissions and safety regulations have necessitated major investments. This is also accompanied by several compliance-related hurdles.
- Global Factors & Export Slowdowns
Geopolitical conflicts and other logistical hurdles are putting the brakes on export volumes and overall profitability. They may cause a possible 5% dip in volumes for FY27.
- Input Costs & Rural Demand
Possible El Niño and other environmental impacts may threaten rural demand, which has long been a growth driver for several categories, like two-wheelers.
- Capacity Management
Despite steady capacity expansion, the sector also faces the challenge of sustainably balancing high inventory levels with a possible cooling in demand growth relative to FY26’s record highs.
Disclaimer: the views expressed here are of the author and do not reflect those of Groww.