Margin of Safety Explained: Definition, Formula & Uses
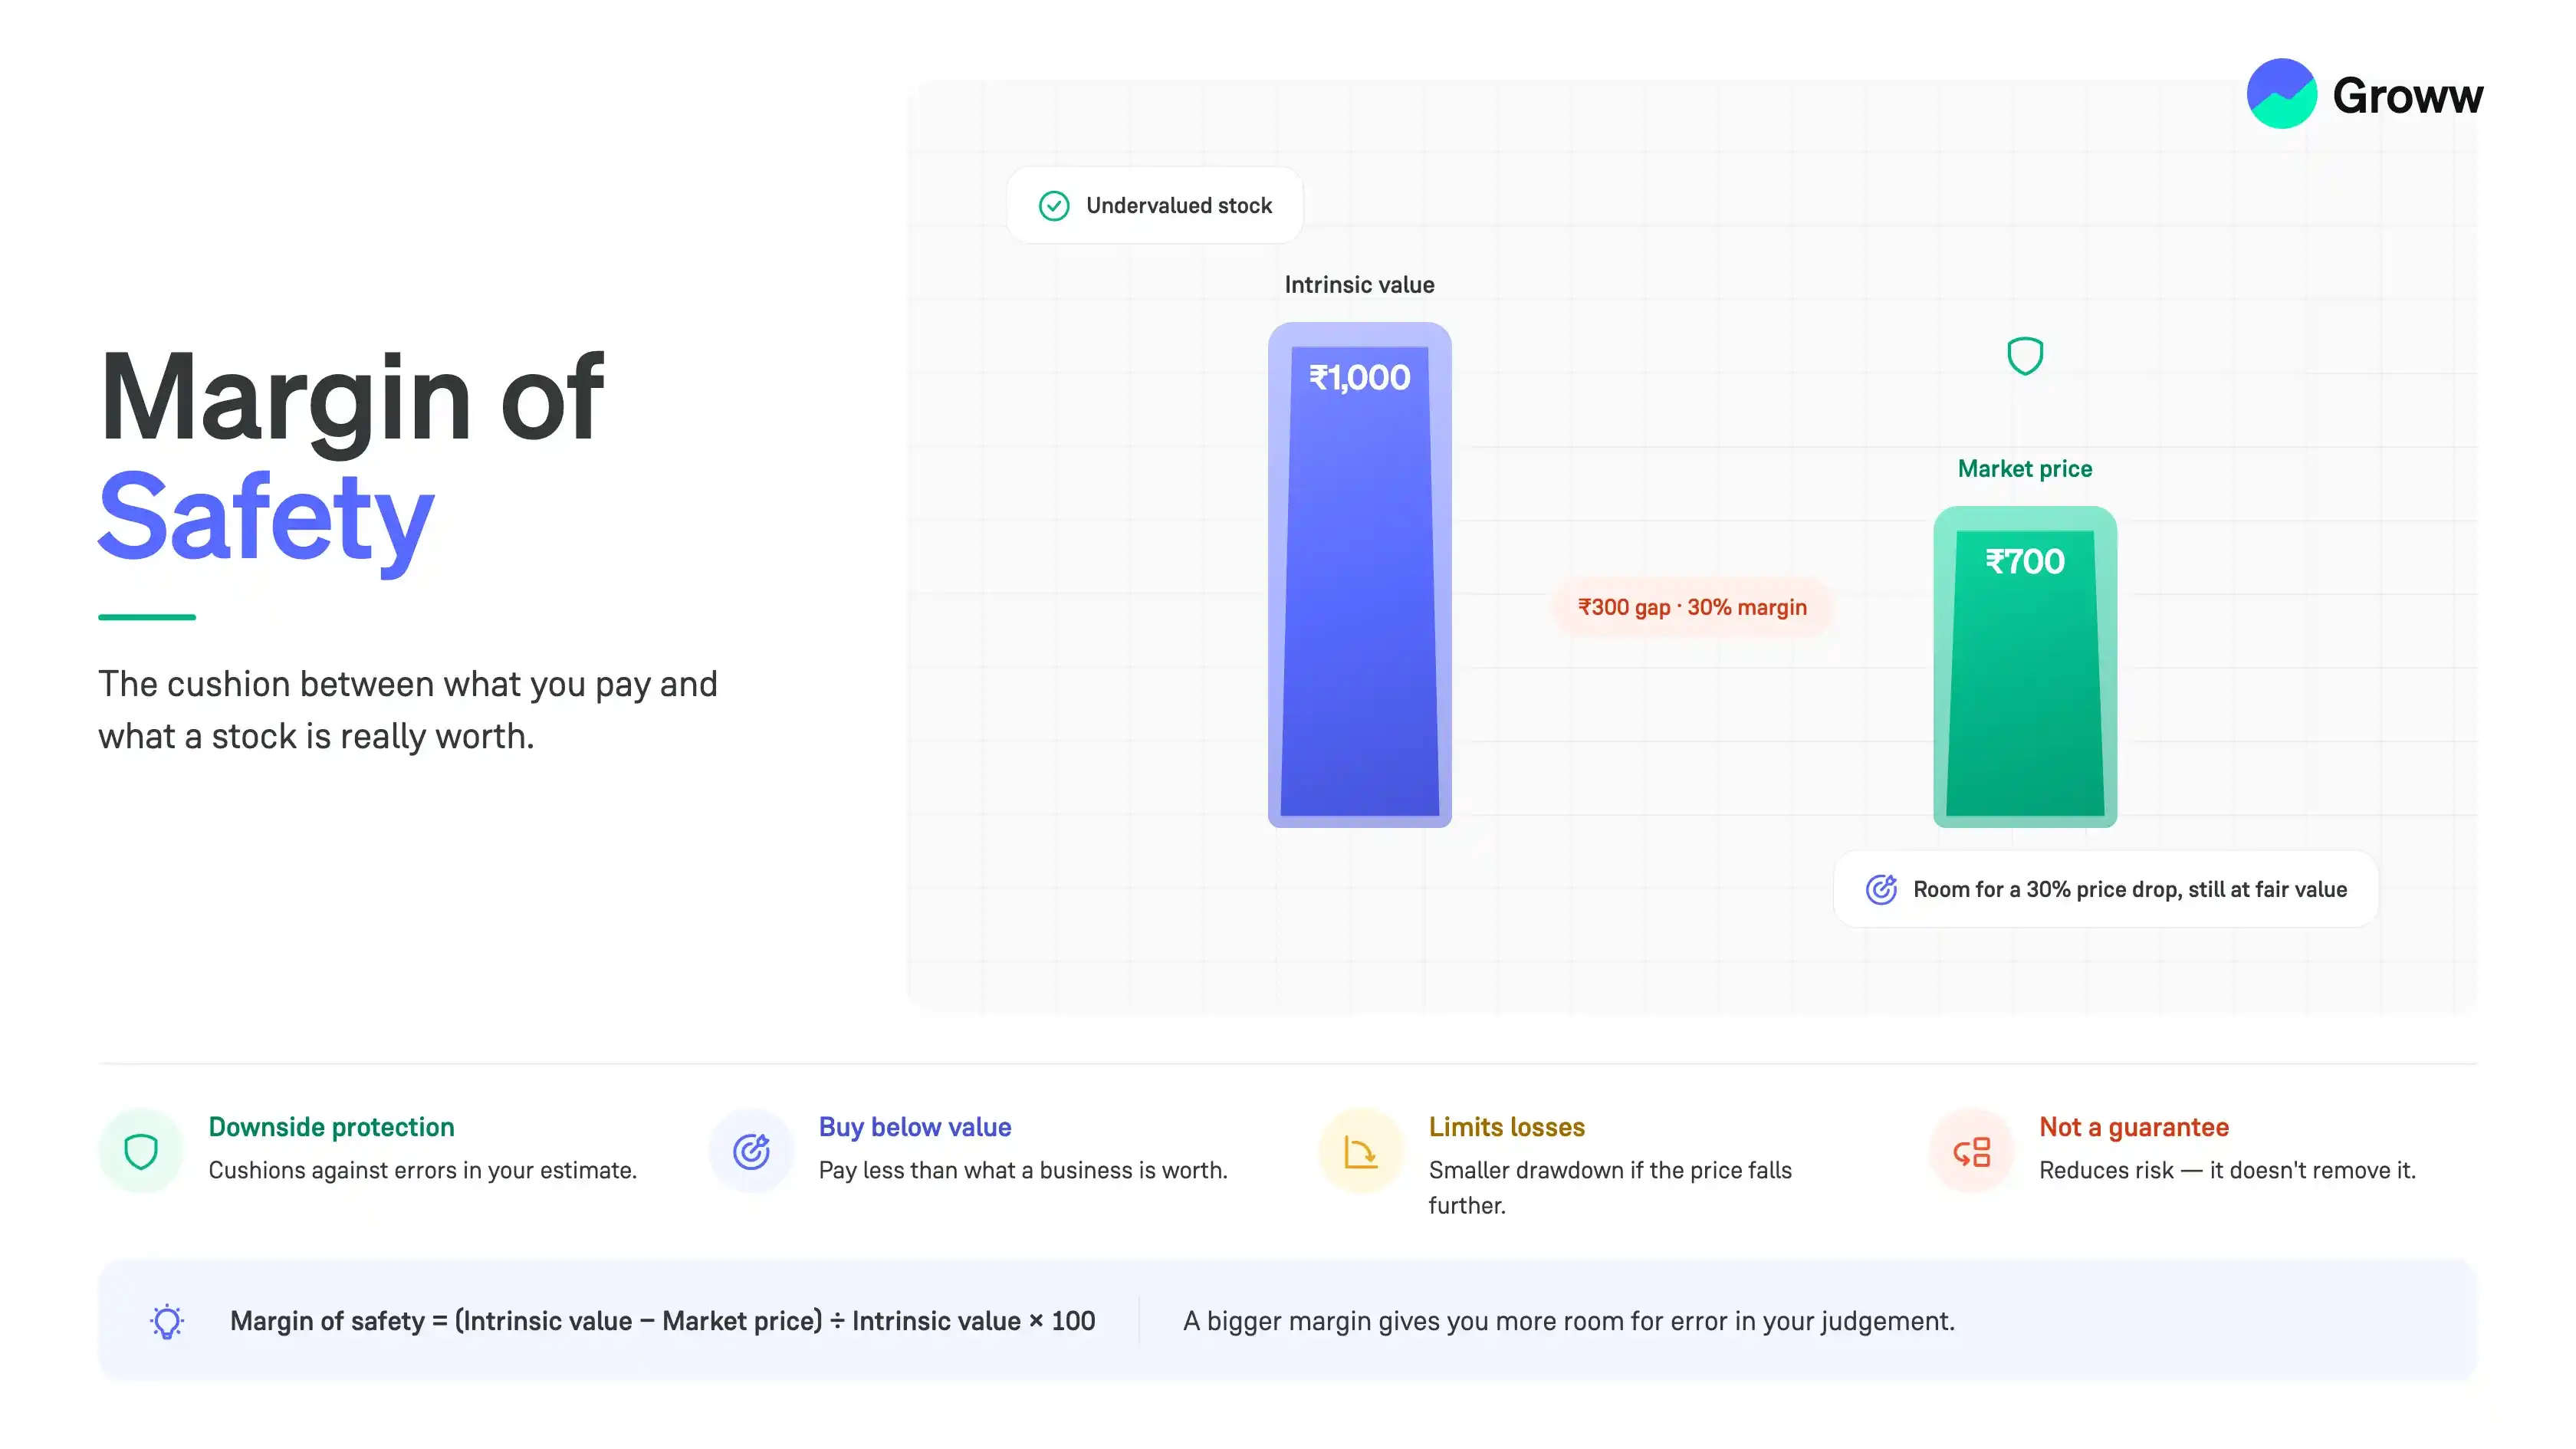


The margin of safety is the difference between a stock's estimated intrinsic value and its market price. It serves as a buffer against analytical errors, market volatility, or poor business performance. The concept was created by Benjamin Graham and dictates purchasing only when there is a significant discount, thereby minimising downside risk.
Intrinsic value is the actual worth of a company based on key fundamentals like assets, dividends, and earnings, independent of the market price. There are several methods used to determine intrinsic value before applying the margin of safety.
Graham’s formula is the most common method, while other methods include earnings power value (EPV) and discounted cash flow (DCF). Graham called the concept the foundation of risk-averse and defensive investing, where it safeguards the investor against emotional reactions to Mr Market, which offers daily irrational prices.
Margin of Safety Formula
You can use the formula below to calculate the Margin of Safety in percentage form.
Formula of Margin of Safety
|
The Margin of Safety (MOS) = 1 − (Current Share Price / Intrinsic Value) |
Say, for example, that an investor believes a company's shares have an intrinsic value of ₹ 600 but are currently trading at ₹ 800. The MOS in this instance is 33%, which means that the share price has a 33% range before it reaches the estimated intrinsic value of ₹ 600.
Why Value Investors Use Margin of Safety
Value investors use the margin of safety to minimise capital loss, mitigate risk, and account for human error in valuation. Here are some of these reasons:
- Safeguarding against errors: Since determining the intrinsic value of a stock is based on estimates, the margin of safety serves as compensation for potentially incorrect assumptions.
- Minimising capital loss: By buying assets at steep discounts to their intrinsic value, investors safeguard against permanent capital losses during market downturns.
- Tackling unknown unknowns: It protects investors against unforeseen events and market volatility.
- Management of psychological bias: Investors can maintain rational decision-making during emotional and destabilising market conditions. It prevents panic selling and other impulsive decision-making.
- Boosting long-term returns: Buying undervalued stocks with a high margin of safety may lead to better risk-adjusted returns over the long term.
Margin of Safety in Investing vs Accounting
The margin of safety works as a protective buffer, although the focus does differ. In investing, it is the discount between a stock's market price and its intrinsic value (to reduce downside risk). In accounting, the sales volume cushion is the amount above the break-even point used to prevent losses.
Margin of safety in investing:
- Formula: 1 - (Market Price/Intrinsic Value)
- Objective: Protecting against incorrect valuations, sudden company setbacks, and volatility in the market
- Market Perspective: Since Indian equities may be volatile, high margins are recommended, i.e. 30% for large caps, 40% for mid caps, and 50%+ for small caps to manage risks.
Margin of safety in accounting:
- Formula: Current sales - Breakeven sales/current sales x 100
- Objective: Used to evaluate risks, forecast sales, and set prices of goods
- Perspective: A higher margin indicates improved financial stability to withstand revenue dips or economic downturns.
So, a 50% margin of safety in investing indicates that you purchased at 50% below value (say at a ₹500 price for a ₹1000 value), while a 50% margin of safety in accounting indicates that your sales may drop by 50% before breaking even.
Application of The Margin of Safety in Investing
- Firstly, in addition to preventing potential losses, the Margin of Safety can increase returns on particular investments. For instance, if an investor buys an undervalued stock, the stock's market price may rise in the future, giving the investor a much higher return.
- Secondly, investors can use the Margin of Safety to compare the company's share price to its current market price and utilize the difference as justification for purchasing securities. It implies that the stock prices have remarkable upside potential.
- Thirdly, the Margin of Safety protects the investor from an unexpected decline in the market. Understanding a stock's intrinsic value is crucial before an investor purchases it at a discount.
Therefore, such an analysis can be carried out by estimating growth rates based on the performance of the business over the years, growth trends, and potential future projections. - Lastly, originally predicted outcomes frequently outperform actual outcomes. Regarding production and sales, the Margin of Safety will be of little use because the business already knows whether it is making money.
Nevertheless, it is helpful as a risk-avoidance tool during the decision-making process.
You may also want to know the Top 5 Technical Analysis Tools for the Stock Market. |
Importance of The Margin of Safety in Accounting
The size of a company's Margin of Safety is crucial to its viability. It illustrates how sales can drop before the company experiences a loss. If the business's Margin of Safety is large, the likelihood that it will suffer a loss is low, but if it is small, even a slight decline in sales could result in a loss.
A high Margin of Safety is frequently preferred because it denotes optimal performance and a company's capacity to withstand market volatility.
Margin of Safety For Accounting/Finance Students
For accounting/finance students, the margin of safety is a vital financial metric that represents the difference between actual (or forecast) sales and the break-even point. It shows you how much revenue may drop and how much loss a company may incur, thereby serving as a cushion against higher risks. A higher percentage, i.e. 20-30%, often indicates lower risks. Some of the main formulas include:
- Margin of Safety (Units) = Actual Sales Units - Breakeven Units
- Margin of Safety (Rupees) =Actual Sales - Breakeven Sales
- Margin of Safety Ratio = (Actual Sales - Breakeven Sales/Actual Sales) x 100
Here are some other key aspects worth noting in this regard:
- A high margin of safety means the company can handle any significant decline in demand.
- The break-even point is the level at which total revenue equals total cost.
- Accounting thus uses a margin of safety to examine sales cushions.
- A 20-25% margin of safety is usually adequate, while 30% or more is considered a robust buffer.
How to Estimate Intrinsic Value
Here’s how to estimate intrinsic value -
- Discounted Cash Flow (DCF): Calculates the present value of all future cash flows expected from the firm.
- Graham Formula: A simplified formula -
EPS (trailing twelve-month earnings) x (8.5 (P/E ratio for a no-growth entity) + 2g (growth rate)) x 4.4 (average yield of AAA corporate bonds in 1962/Y (present AAA bond yield)
- Price-to-Earnings (P/E) Ratio: This is calculated by multiplying the company’s EPS (earnings per share) by the industry-average P/E ratio.
- Comparable company analysis: It is done by comparing valuation multiples (such as EV/EBITDA and P/E) to industry peers.
Simple Intrinsic Value Example
Let’s say a company called Company X has an estimated intrinsic value (based on DCF/earnings) of ₹1,000 per share. The current market price stands at ₹700 per share.
In this case, the margin of safety (amount) will be ₹300 while the percentage will be the following:
(1,000-700/1,000) x 100 = 30%.
Hence, you may incur a valuation error or share prices may drop by 30%, thereby underperforming your expectations before you incur a capital loss.
Purchase Price Calculation After Applying 20% / 25% / 30% MOS
You can apply this formula for the calculation:
Purchase Price = Intrinsic Value x (1 – MOS Percentage)
Let’s assume a company has an intrinsic value of ₹1,000 per share.
20% Margin of Safety:
Maximum Purchase Price = 1,000 x (1 – 0.20) = 1,000 x 0.80 = ₹800
25% Margin of Safety (commonly used by Graham/Buffet):
Maximum Purchase Price = 1,000 x (1 – 0.25) = 1,000 x 0.75 = ₹750
30% Margin of Safety (slightly more conservative):
Maximum Purchase Price = 1,000 x (1 – 0.30) = 1,000 x 0.70 = ₹700
When to Use DCF, DDM, and Residual Income
- DCF (Discounted Cash Flow):
It has to be used for stable, mature companies with predictable cash flows, or growth entities with clear, forecastable future projects. For margin of safety, apply a higher discount rate to the terminal value to safeguard against overestimating long-term growth. It is ideal for free cash flow to the firm (FCFF) or equity (FCFE).
- Dividend Discount Model (DDM):
This values a stock based on the current value of future dividends. You can use it for mature, stable companies that pay predictable, regular dividends, e.g., utilities, banks, REITs, etc. For the margin of safety, you should use a more conservative and lower dividend growth rate. This is ideal for dividend-paying mature firms.
- Residual Income (RI) Model:
It helps calculate value by adding the current value of future excess returns (income generated over the cost of capital) to the present book value. You can use it for companies with no dividends, unstable dividends, or negative free cash flows (but with positive book value and anticipated earnings). It may offer a more conservative and stable valuation than DCF, since it relies heavily on book value rather than the long-term terminal value. It is ideal for companies with high intangibles or low cash flow, as well as banks and financial institutions.
Intrinsic Value and Target Buy Price Example
Here is an example of the intrinsic value and the target buy price for your understanding -
Let’s take a stable Indian FMCG company (Company A) that is listed on the National Stock Exchange (NSE) in 2026.
Say the current market price (CMP) is ₹1,000. The target in this case is to work out whether it’s a Buy based on a 30% margin of safety. Calculate the intrinsic value or the present value of future cash flows.
So, if the earnings per share (EPS) are ₹30, the expected growth rate (5 years) is 12%, and the discount rate (required return) is 10%, the estimated intrinsic value can be worked out through the DCF model. This can be estimated at ₹1,250.
Now, apply the target margin of safety, i.e. 30%, which means that the target buy price is ₹875.
Since the current market price is above the target buy price, the stock does not yet have sufficient margin of safety. Ideally, you could consider waiting for the price to drop to close to ₹875 before you buy.
Finding the Right Margin of Safety for Your Investments
Based on the company size, you could have a margin of safety as follows :
- Large Caps (Stable firms): ~30%
- Mid-Caps (Moderate growth/stability): ~40%
- Small-Caps (Cyclical/high-risk): ~50% or higher
- Distressed Cases/Turnarounds: 60% or higher
Limitations
One limitation of intrinsic value is its assumption-heavy nature. It mainly relies on the accuracy of the estimated intrinsic value, which makes it subjective.
Determining the true worth of any entity involves forecasting the future cash flows, terminal values and growth rates. If the inputs are inaccurate or overly optimistic, the margin of safety becomes misleading or illusory.
A large margin of safety on the surface does not protect you if the company's fundamentals are in poor shape. A low price may indicate distress instead of a bargain in a shrinking sector.
Unknown-unknowns or unforeseeable scenarios cannot be fully eliminated by a margin of safety.
A high margin of safety may also lead to buying a value trap, where a stock seems affordable even though its price never converges on its intrinsic value. It thus remains underpriced for several years.
The approach is often suited to asset-rich, stable entities rather than fast-growing companies in sectors like technology, where it’s difficult to forecast future cash flows.
Measures to Improve an Unsatisfactory Margin of Safety:
Contrary to a high Margin of Safety, a low margin of safety might signify a precarious financial position and needs to be improved by raising sales. It will protect the investors from mistakes and bad choices. Higher fixed costs are a common reason why margins of safety are lower.
Such businesses require a high level of activity. The following actions may be taken to increase an inadequate Margin of Safety because a low Margin of Safety is cause for concern-
- Boost the selling price.
- Reduce the variable costs, the fixed costs, or both.
- By using the underutilized production capacity, the output volume can be increased.
- Put an end to the production of unprofitable products and focus only on those that are.
Significant Factors to Remember About the Margin of Safety
- A Margin of Safety is a constructed safety net that allows some losses to be accumulated without having a significant negative impact.
- The Margin of Safety combines quantitative and qualitative factors to evaluate a target price and a safety margin that involves reducing that target in investing.
- With buying shares at price levels well below their target, a Margin of Safety is built in particular instances where estimates were inaccurate or biased.
- The Margin of Safety is constructed into break-even forecasts in accounting to allow for some wiggle room in those estimates.
Comparison Between Market Price, Fair Value, and Target Price
The market price is the present trading price on the BSE or NSE, while fair value is the calculated true worth of a company based on assets and cash flows. The target price is a forward-looking estimate (often 12 months) of where analysts anticipate the stock price to go.
Here is a comparison table you can use for reference:
|
Aspect |
Market Price |
Fair Value |
Target Price |
|
Source |
Exchange market |
Investor/analyst calculation |
Sell-side analyst estimate |
|
Nature |
Objective (fact) |
Subjective (opinion) |
Predictive (estimate) |
|
Timeframe |
Present (instant) |
Long-term (fundamental) |
Short-to-medium term |
|
Usage |
Transaction price |
Valuation anchor |
Selling/profit booking goal |
|
Role in Margin of Safety |
Deducted from intrinsic value |
Calculation baseline |
Not usually used |
Difference Between Accounting and Investing MOS Logic
Here are the main differences between the accounting MOS formula and investing MOS logic:
|
Aspect |
Accounting MOS |
Investing MOS |
|
Focus Area |
Operational risks (sales vs cost) |
Valuation risk (price vs value) |
|
Main Objective |
Bypass operating losses |
Bypass permanent capital loss |
|
Components of the Formula |
Actual sales and breakeven point |
Market price and intrinsic value |
|
Nature |
Formulaic and quantitative |
Analytical and subjective |
|
Timeframe |
Short-term or routine |
Long-term |
Conclusion
Summarizing the above, the investment experts are advocating conservatism by propagating the Margin of Safety concept. Buying at a discount to the real business value by giving maximum weightage to the worst-case scenarios seems to sum up the value investing approach.
The Margin of Safety can be a valuable approach to wealth conservation in the long run, whereby one does not lose all or most of the money by investing in stocks.
Graham’s words echo this sentiment: “For indeed, the investor’s chief problem – and even his worst enemy – is likely to be himself….” “The fault, dear investor, is not in our stars – and not in our stocks – but in ourselves….”