Treasury Stock: Meaning, Accounting & Why Companies Buy Back Shares
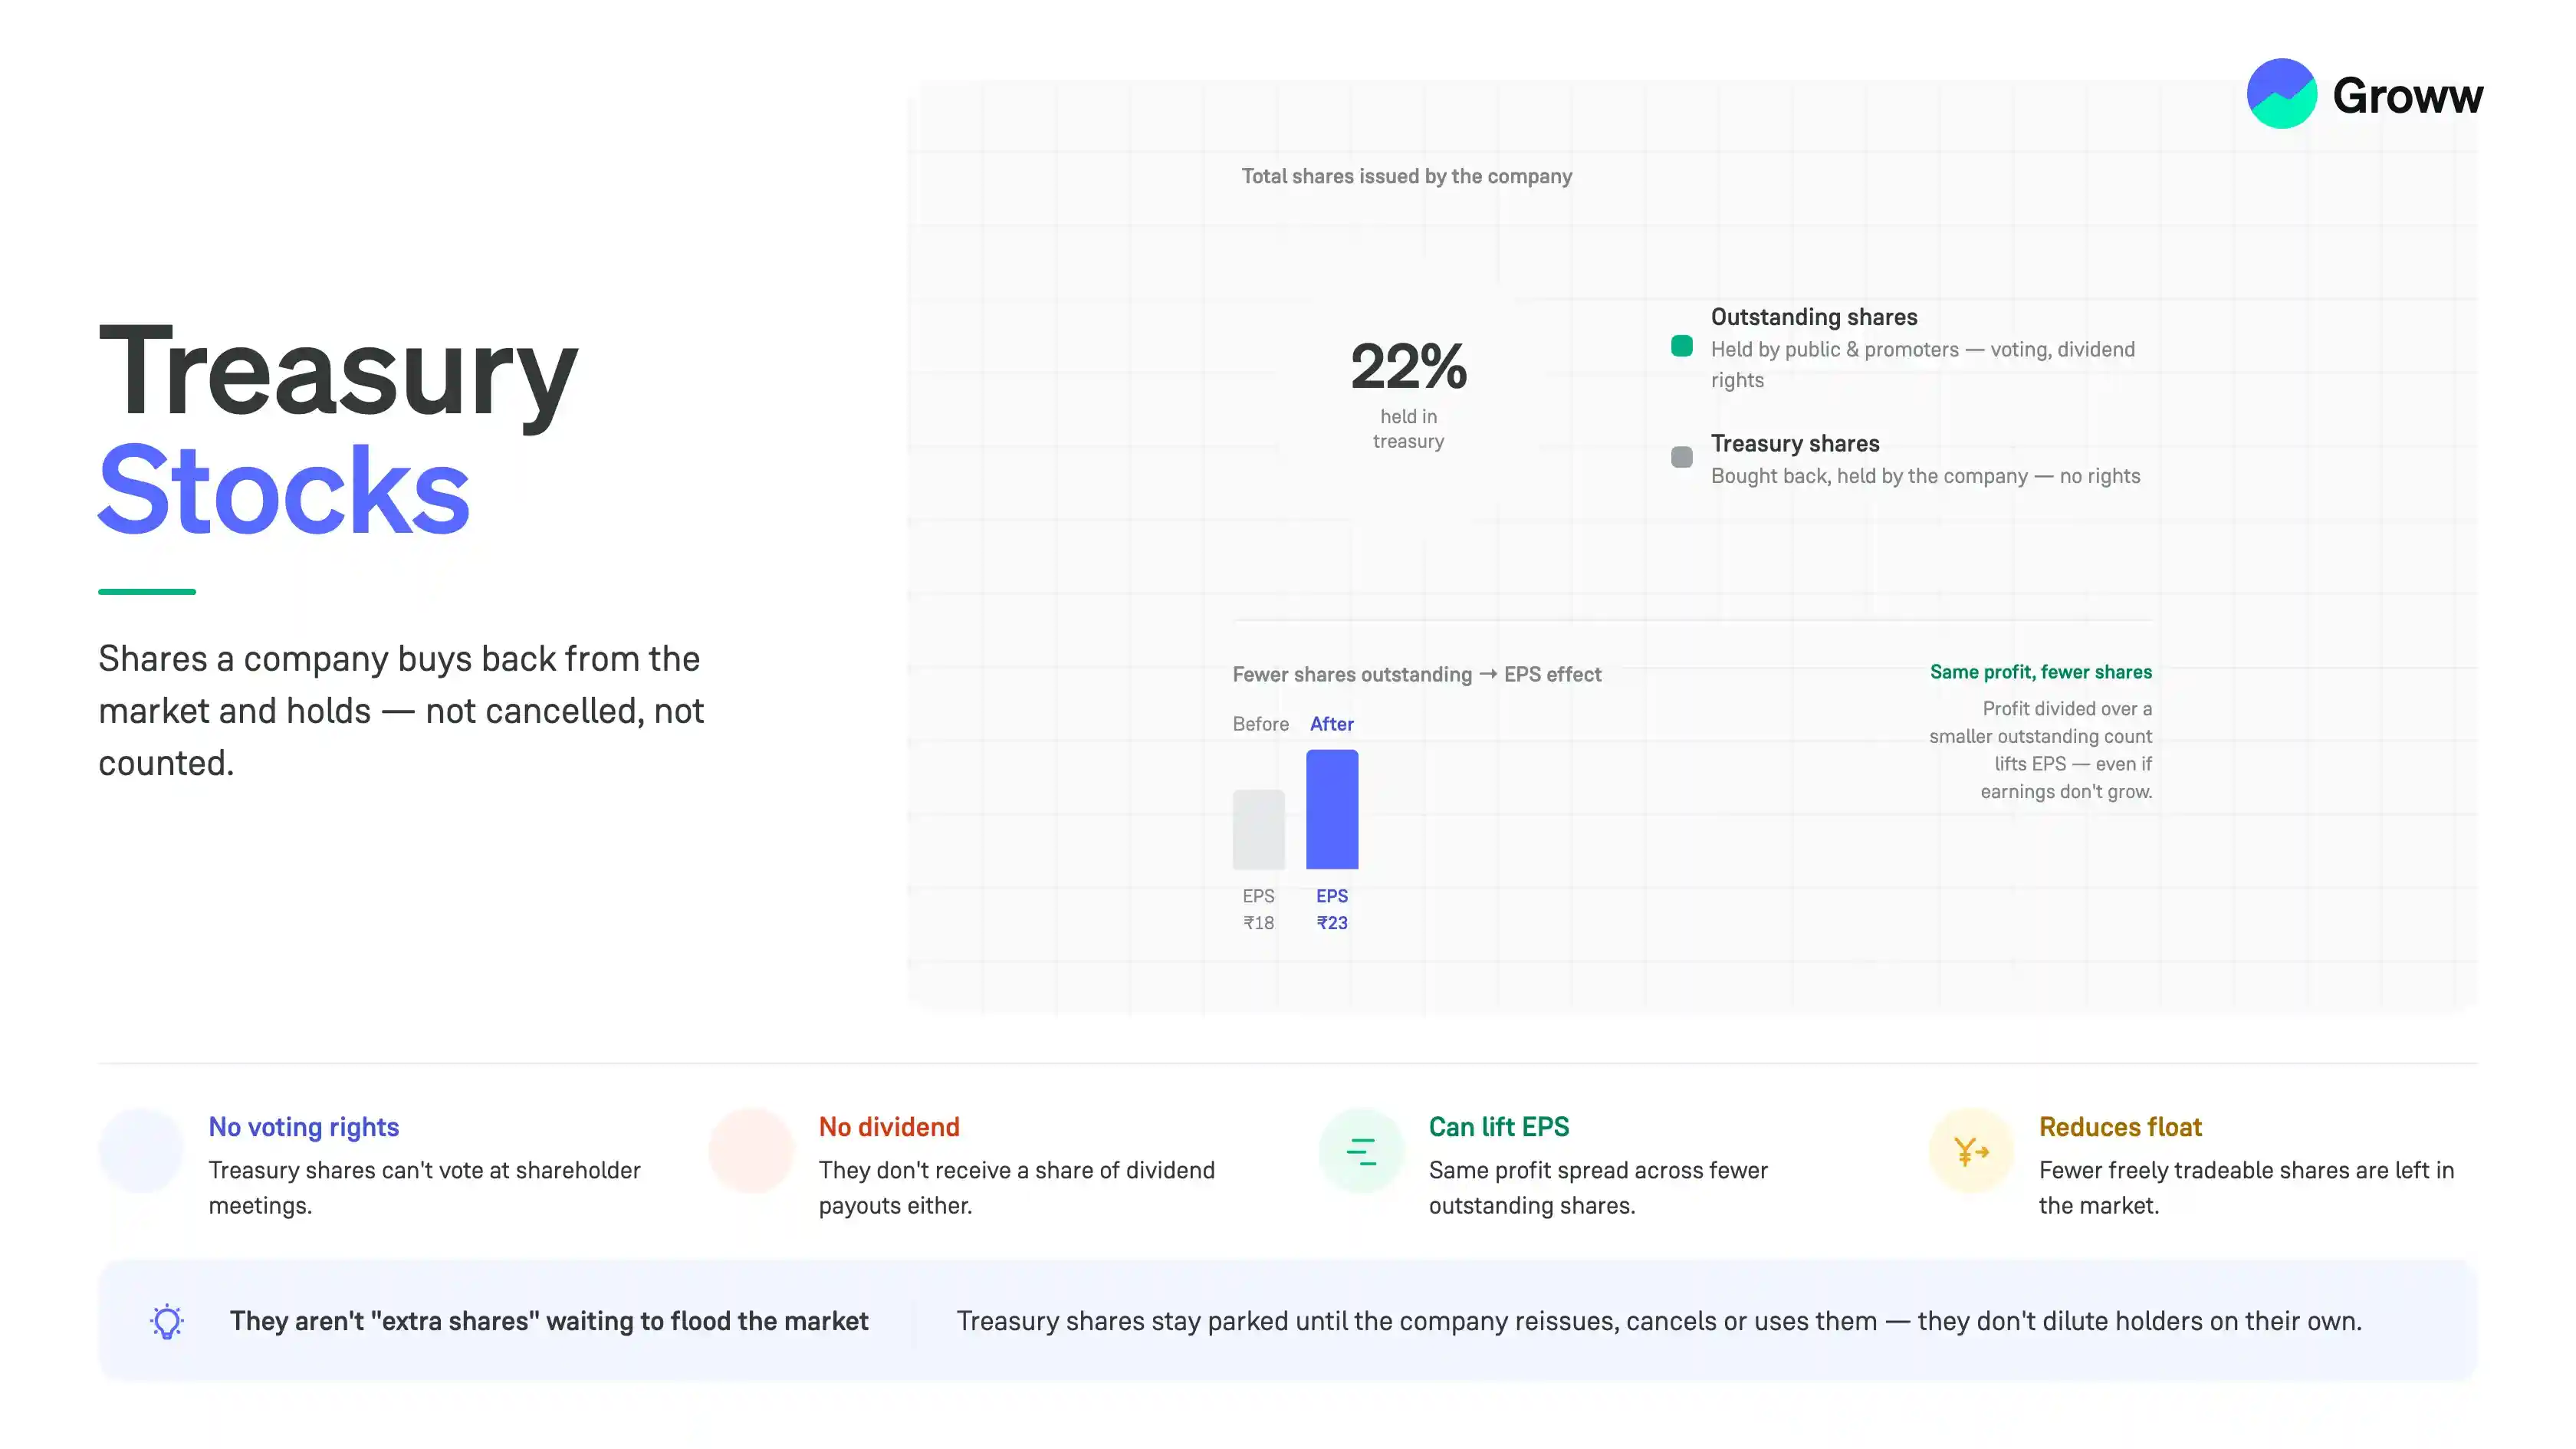


Treasury stocks, also known as reacquired stocks, are the portion of a previously issued stock that a company has purchased (bought back) from its shareholder. These stocks are held by the company and are used for its disposition.
These stocks can remain in the company’s possession or may also be used for future issuing to prospective shareholders. Also, a company may decide to retire these shares permanently from the market; thereby, they will not be available for any use.
Where is a Treasury Stock Reported?
The treasury stock finds a mention in the balance sheet under the shareholder’s equity section. It is one of the various types of equity accounts and is generally mentioned as a contra-equity account.
Understanding The Framework Of Treasury Stocks
Every company is allowed to issue a certain number of shares. These shares are called “outstanding shares.”
Of these shares, some are publicly traded, whereas some are restricted shares (it means that these shares can’t be sold unless certain conditions are fulfilled).
Treasury stocks are the stocks that are initially a part of outstanding shares and were held by an entity (individual or organization). However, these shares are repurchased by the company from its shareholders.
Why Do Companies Conduct Share Buybacks?
Treasury stocks refer to shares that a company buys back from the open market. This reduces outstanding shares, enhancing EPS (earnings per share) while boosting financial ratios and supporting stock prices when they are undervalued.
Companies also use them to combat hostile takeovers and optimise their capital structures. They often retire them or hold them for future employee compensation. Let us look at some of the main reasons why companies buy back shares:
- Increasing Shareholder Value: By reducing the number of outstanding shares, EPS (earnings per share) and ROE (return on equity) increase, thereby enhancing the stock's attractiveness.
- Utilisation of Excess Cash: Companies that have surplus cash and no profitable or immediate investment opportunities often return value to their shareholders via buybacks (instead of dividends).
- Undervaluation Aspects: When management believes the market has undervalued their stock, a buyback is often a signal of confidence and supports the share price.
- Combating Hostile Takeovers: Buying back shares increases the promoter's ownership percentage. This makes it more difficult for outsiders to acquire controlling interests in the company.
- Employee Compensation: Entities may reissue treasury shares for employee stock option plans or ESOPs. This can be done without diluting the existing shareholders.
Yet, there is a distinction between Indian and global accounting concepts that needs to be understood in this context. Here is a table that will illustrate it better for you:
|
Key Aspect |
Indian Ecosystem (Companies Act 2013/Ind AS) |
Global/US Landscape (US GAAP/IFRS) |
|
Share Treatment |
Repurchased shares are often instantly retired or cancelled, lowering authorised capital |
Repurchased shares are often held in treasury, and they may be reissued later |
|
Impact On the Balance Sheet |
Debited to free reserves or share premium accounts, thereby lowering shareholder equity |
Recorded as a contra-equity account (treasury stock). This lowers the total equity |
|
Subsidiary Holding |
Stringent regulations and it is usually not allowed unless any specific exemptions are applicable |
The subsidiary may hold the parent shares, although these are eliminated upon consolidation |
|
Buyback Costs |
Often charged to P&L, although amortising and capitalising are often some options |
Direct deductions from equity and not routed via P&L |
You should note that buybacks are stringently regulated in India under Section 68 of the Companies Act, which requires compliance with the debt-equity ratios.
Also, while buybacks may enhance stock prices, they may also lower the free float of shares, thereby restricting trading liquidity. There are also concerns that over-leveraged companies use buybacks to manipulate stock prices rather than invest in growth.
Understanding Treasury Stocks in Financial Statements
The first thing to understand before we get onto the balance sheet is the geographical implications of treasury stocks. It is primarily a global or US-based accounting concept. This is the US GAAP mechanism under which the reacquired shares will be held in a treasury account for resale or reissuance later.
However, in India, under the Companies Act of 2013, shares bought back are usually intended to be eliminated and destroyed within a specified period rather than being held. This means they are not considered treasury stock in the conventional sense. Hence, Indian investors should carefully examine how local buybacks are disclosed.
So, under Section 68 of the Companies Act, shares bought back in India should be physically cancelled or extinguished within 7 days of the last date of completion of the buyback. Companies in India cannot own their shares in the same way as they own their assets.
Here’s how you can cross-check Indian buybacks:
- CRR (Capital Redemption Reserve): When a buyback occurs, Indian entities must transfer the nominal value of the shares repurchased to this CRR. It may only be used for the issuance of bonus shares. It ensures that the capital base reduction is recognised.
- Lowered Paid-Up Capital: The financial statement notes will show a reduction in issued and paid-up capital and a corresponding reduction in cash/bank balances.
- EPS Impact: Although shares are cancelled, the lower number of shares outstanding may enhance EPS (earnings per share). This makes the stock appear more valuable.
So, when an Indian company announces its buyback, don’t anticipate Treasury Stock on the balance sheet. Rather, look for a reduction in the paid-up capital and cash, along with an increase in the Capital Redemption Reserve. Also, look for a reduction in the overall number of outstanding shares.
Balance Sheet Treatment (Treasury Stocks):
- The US GAAP records at cost as a reduction of the equity of the total shareholders and may remain on the books for years. In India, bought-back shares are mostly cancelled within 7 days of acquisition, and this instantly lowers issued share capital.
- In both the US and Indian jurisdictions, they are not considered company assets.
- Treasury stocks will lower the overall number of outstanding shares and decrease the company’s net worth.
- In terms of valuation, they are recorded at cost rather than at market value.
- Repurchased shares held in the treasury do not receive any dividends or carry any voting rights.
- In India, under Ind AS and the Companies Act, they are deducted from equity, often due to employee stock options or buybacks.
So, in India, companies may hold the same to reduce equity dilution or permanently cancel them, thereby increasing the value of the remaining shares.
In a US balance sheet, it may appear like this:
Shareholders’ Equity
Common Stock = $10,000
Retained Earnings = $50,000
Less = Treasury Stock ($5,000)
Total Equity = $55,000
How Do Companies Buyback Stocks?
A stock buyback or repurchase (as it is called usually) is a methodology by which the management of a company can reduce the number of outstanding shares circulating in the market. The company’s remainder shareholders are likely to benefit owing to the rise in relative ownership. Following are the methods by which a company may carry out the repurchase:
Tender Offer
A company offers to repurchase the shares from existing shareholders at a specified price that the company is willing to pay. This specified price is generally at a premium to the market price. The company also discloses the duration for which the buyback offer is valid. Once the tender offer is released, the shareholders who are willing to sell their holdings in the company may tender their shares within the due date for repurchase.
Open Market Operation
Also known as direct purchase, the open market operation is nothing but buying back the shares directly from the exchange. Whenever a company announces a buyback, the action is generally considered positive, thereby leading to an increase in the share price. The company then proceeds to purchase the shares like any other investor in the market.
Dutch Auction
In this route, the company announces its willingness to buy back its shares. Also, the company announces the price range in which it is looking to repurchase the shares along with the date range in which the offer is valid.
An existing shareholder who is willing to participate may tender his/her interest with a price from the defined price band. Once the company receives the interest of all shareholders, it purchases the desired number of shares for the lowest cost possible. This is done by reviewing the offer given by the shareholder.
Comparing the Cost Method and Par Value Method
Understanding the cost method or par value method is important when handling treasury stocks. The cost method records shares at the purchase price (in a contra-equity account), and the par value method removes stock at par value while reversing original APIC (thereby lowering equity at par value).
Cost Method:
- Acquisition: Debit Treasury Stock (at cost), Simplifies tracking cost, Credit Cash.
- Reissuance: Gain recorded in APIC-T/S, the losses reduce APIC-T/S and then the Retained Earnings (RE).
- Focal Point: The amount that is paid to acquire the shares.
Par Value Method:
- Acquisition: Treasury Stock is debited at Par. The original APIC is removed. The difference between the cost and par impacts the APIC-T/S or the RE.
- Reissuance: Similar to the issuance of the original stock.
- Focal Point: Treasury stock is treated as if retired, then reissued.
So, under the cost method, treasury stock is a contra-equity account (full cost), while under Par, it is treated as a reduction in the components of individual equity. The cost method recognises the gains/losses on reissuance, while the Par value method recognises them upon repurchase. The cost method is more commonly used in practice.
Retired Shares and Treasury Shares: Key Differences
Retired shares are repurchased stocks that are permanently cancelled, thereby reducing the total number of authorised shares.
In comparison, treasury shares are repurchased shares held for future reissue, e.g., in mergers and employee options. This reduces outstanding shares but not the authorised shares. It is not possible to reissue retired shares without any shareholder approvals.
Key differences between treasury shares and retired shares include -
- Status: Retired shares are legally cancelled, while treasury shares are unissued but active.
- Balance Sheet: Retired shares lower APIC/common stock instantly, while treasury stock appears as a contra-equity account (lower shareholder equity).
- Future Usage: Treasury shares may be reissued or resold, while retired shares cannot.
- Effect: Retiring shares reduces the overall number of authorised shares, which may indicate lower future dilution for investors.
- Accounting Treatment: For retiring shares, the original issuance entry is reversed, thereby debiting the APIC (Additional Paid-in Capital) and Common Stock. Treasury stock is recorded at cost (through the par value or cost method) while sitting in the treasury stock account until it is sold.
The Impact of Treasury Stocks on EPS and Shareholder Rights
Treasury stocks have the following effects on EPS, voting rights and dividends:
- EPS (Earnings Per Share): Since treasury shares are not perceived as outstanding, the denominator in the EPS calculation will decrease. If net income remains unchanged, EPS goes up. Treasury stocks usually result in higher EPS.
- Voting Rights: Treasury shares cannot vote on any corporate matters.
- Dividends: Treasury shares are not entitled to receive any cash dividends.
In the Indian context, companies must cancel repurchased shares within 7 days of the buyback. In the balance sheet, the shares are cancelled, thereby lowering the share capital. The focus here is on reducing capital with restrictions on its strategic use. Ownership is cancelled, with the shares being fully removed from ownership.
Treasury Stock vs Buyback vs Share Cancellation
Let us look closely at the major differences between treasury stock, buyback and share cancellation.
|
Key Aspect |
Buyback |
Treasury Stock |
Share Cancellation |
|
Meaning |
The company buys back its own shares |
Repurchased shares are kept in inventory |
Repurchased shares are eliminated |
|
Status |
Action/Transaction |
Held Asset/Contra-Equity |
Permanently Retired |
|
Future Usage |
N/A |
May be resold/reissued |
Cannot be reissued |
|
Balance Sheet |
Lowers Cash/Equity |
Recorded at cost (contra-equity) |
Lowers Share Capital/Retained Earnings |
|
Objective |
Increase the EPS, return cash |
Stock options and acquisitions |
Permanently boost financial ratios |
A buyback is the purchase of shares in the open market, thereby reducing the number of outstanding shares.
Treasury stock is the repurchased shares held by the company for future use without any dividends or voting rights.
Share cancellation involves retiring shares, which permanently reduces the company's issued share capital.
Understanding Treasury Shares in the Context of Indian Listed Companies
Here are some of the key things that you need to look out for when analysing Indian listed companies:
- Effect on the Valuation Ratios: When treasury shares are excluded from the EPS calculation, this increases EPS for the remaining shares. This makes the company seem more profitable (per-share basis).
- Effect on the Balance Sheet: They are reflected as a reduction in total shareholders' equity. High treasury stock levels reduce the overall equity base, which may inflate ROE and the debt-to-equity ratio.
- Strategic Usage: Companies often hold these shares for acquisitions, mergers, or to meet ESOP (Employee Stock Option Plan) requirements. This may be more tax-efficient compared to issuing new shares.
- Regulatory Evaluation: SEBI (Securities and Exchange Board of India) has stringent regulations governing the limit on the number of shares a company may buy back. This is done to prevent any misuse.
Always try to find out whether the company is buying back shares because it is undervalued or to artificially boost the share price during a slump. Examine whether this is the best use of capital, or whether it could be used to reduce debt or fund growth (CAPEX).
You should also not confuse treasury stocks with Government Treasury Bills, and note that companies in India must adhere to stringent processes under the Companies Act for any buybacks.
Outstanding Shares Before and After Buybacks
It is essential to note the impact on outstanding shares on a before/after basis. Let us look at the same below:
- Before Buyback: Total outstanding shares = Total issued shares – (earlier held treasury shares).
- After Buyback: Total outstanding shares = (Previous outstanding shares) – (Number of shares repurchased).
Impact on Earnings Per Share (EPS)
Here’s an example of how earnings per share (EPS) are impacted -
ESOP Dilution:
- Net Income = ₹100 Crore
- Basic Shares Outstanding = 10 Crore
- Exercise Price of Options = ₹200
- Average Market Price of Share =₹500
EPS Calculation (Basic) = Net Income/Shares Outstanding = ₹100 Crore/10 Crore
EPS = ₹10.00 per share
Treasury Stock Method (Diluted EPS):
- Step 1
Total Proceeds = 1 Crore Options x 200 (Exercise Price) = ₹200 Crore
- Step 2
Shares Repurchased at Market Value Calculation = Proceeds/Average Market Price
= 200 Crore/₹500
= 0.4 Crore Shares
- Step 3
Net New Shares (Dilution) = New Shares Issued - Shares Repurchased
= 1 Crore - 0.4 Crore
= 0.6 Crore Shares
- Step 4
Calculation of Diluted EPS = Net Income/Basic Shares + Net New Shares
= 100 Crore/10 Crore + 0.6 Crore
= 100/10.6
= ₹9.43 per share
Effect:
- Basic EPS = ₹10.00 (no effect)
- Diluted EPS =₹9.43 (dilutive effect, which is lower than basic)
- Reason for Drop: Although the company bought back 0.4 crore shares, the net increase of 0.6 crore shares enhances the denominator (outstanding shares), thereby lowering the earnings per share (EPS)
Under Ind AS 33, this method is mandated for dilutive potential equity shares, such as employee stock options. This ensures more transparent reporting of company-level profitability.
Impact on Shareholder Equity
Treasury stock reduces total shareholders' equity because it is recorded as a contra-equity account. When the company repurchases its own shares, the cost will be debited, lowering both cash and the overall balance sheet’s equity. It is thus perceived not as an asset but as a reduction in capital.
Here are some of the key impacts on overall shareholder equity:
- Reduction of Equity: Treasury stock directly reduces total shareholders’ equity on the balance sheet.
- Contra-Equity Designation: This is recorded as a negative amount in the equity section, indicating that the company has retired capital from circulation (and not acquired any revenue-generating asset).
- Reduction in Outstanding Shares: Even though issued and authorised, treasury shares are not considered outstanding, thereby reducing the share count used in calculations.
- Reissuance Effect: If treasury stock is resold at a price greater than its cost, equity increases through additional paid-in capital.
- Retirement: Retiring treasury stocks will permanently eliminate shares, thereby lowering both the specific capital accounts and treasury stock balance.
Balance Sheet Example
Here is a balance sheet example from the Indian context:
Balance Sheet Extract (As of March 31, 2026)
|
Liabilities / Shareholders' Equity |
Note |
₹ (in Lakhs) |
|
Shareholders' Equity |
||
|
(a) Share Capital |
₹1,000 |
|
|
(b) Reserves and Surplus |
₹5,000 |
|
|
Less: Treasury Stock (100,000 shares at cost) |
(1) |
(100) |
|
Total Shareholders' Equity |
₹5,900 |
Key Accounting Entries
Key accounting entries (cost method) can be summarised as follows:
Treasury Stock Purchase:
- Debit - Treasury Stock (price paid)
- Credit - Cash (price paid)
- Impact - Lowering total stockholders’ equity
Reissuing Treasury Stock Above Cost (Gain):
- Debit - Cash (amount received)
- Credit - Treasury Stock (cost of shares)
- Credit - Additional Paid-in Capital (APIC)- Treasury Stock (excess over cost)
Reissue Treasury Stock Below Cost (Loss):
- Debit - Cash (amount received)
- Debit - APIC-Treasury Stock (up to the amount credited earlier)
- Debit - Retained Earnings (if loss surpasses earlier gain)
- Credit - Treasury Stock (cost of shares)
Retirement of Treasury Stock:
- Debit - Common stock (par value)
- Debit - APIC-Common Stock (original premium)
- Credit - Treasury Stock (cost)
- Credit - Retained Earnings (if the cost is less than the original price) or Debit
- APIC: Treasury Stock/Retained Earnings (if the cost is more than the original price)
Use Cases of Share Buybacks in India
Here are some key use cases that emerge in an Indian context.
- Employee Compensation Plans (ESOPs): Indian entities frequently repurchase shares for holding in treasury for issuance as per ESOP schemes. Instead of issuing new shares and diluting the existing shareholders, they leverage these treasury shares to reward employees. This directly connects stock performance to compensation.
- Capital Management and Optimisation: Entities with excess cash, especially in mature segments, may use share buybacks to reduce capital. This may improve financial ratios, such as ROE (return on equity) and ROA (return on assets). This is seen as a tax-efficient way to return capital as compared to dividends.
- Anti-Dilution and Control: By purchasing shares in the open market, entities may prevent dilution of existing shareholders when shares might otherwise be issued to external parties.
- Signalling and Price Support: When management believes its shares are undervalued, a treasury buyback may signal market confidence. This may support the stock price during any downturn.
Limitations Of Treasury Stocks
Treasury stocks come with certain restrictions. Following are the limitations of such stocks –
- Comes with no voting rights
- Not entitled to any dividend
- Not a part of outstanding shares computation
- No preemptive rights as a shareholder
- Not entitled for receiving the net assets of the company upon liquidation
- Regulatory angle around treasury stocks
Not all countries have laws governing treasury stocks, but some countries have put in place some regulations around the stock category. In some countries, the number of treasury stocks cannot exceed the maximum proportion of capitalization specified by law.